Adoption of Digital Financial Services in Nigeria has risen to 64.4% of the adult population, bringing the number of citizens using digital channels to 77.0 million. According to findings from the 2026 Access to Financial Services (A2F) survey, released by EFInA and supervised by the National Bureau of Statistics (NBS),……
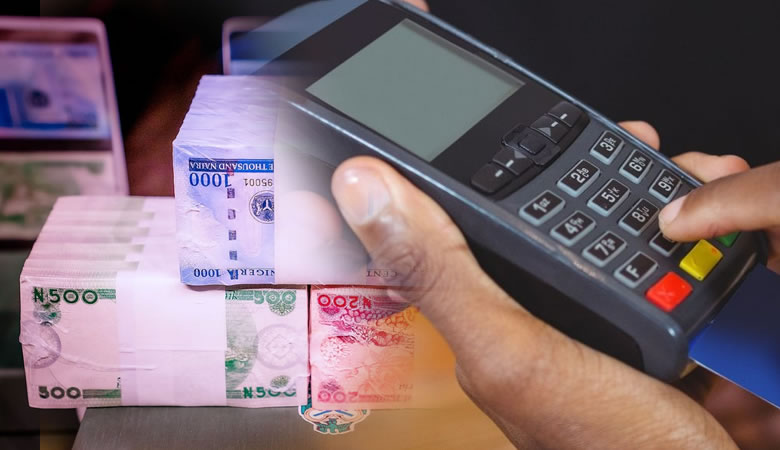
Adoption of Digital Financial Services in Nigeria has risen to 64.4% of the adult population, bringing the number of citizens using digital channels to 77.0 million.
According to findings from the 2026 Access to Financial Services (A2F) survey, released by EFInA and supervised by the National Bureau of Statistics (NBS), digital channels have become mainstream financial infrastructure, up from 45% coverage in 2023.
However, national data indicate that this digital growth remains unevenly distributed, marked by widening urban-rural gaps and severe regional gender divides. While digital payment adoption reached 78% in urban centres, rural adoption stood at 47%, leaving a 31-percentage-point rural digital gap. Across the broader formal inclusion spectrum, the urban-rural disparity widened from 24 percentage points in 2023 to 27 percentage points in 2026. Nationwide, 70.5% of men utilise digital financial channels compared to 58.0% of women, representing a 12.5-percentage-point gender gap. Regional disaggregation reveals that digital gender disparities are most pronounced in northern Nigeria.
In the North West, digital financial service adoption among women stands at 31.0% compared to 54.8% for men, producing a 23.8-percentage-point gender divide. Formal inclusion in the region similarly shows a 20.5-percentage-point gap (72.2% for men versus 51.8% for women). In the North East, female DFS usage trails male usage by 14.9 percentage points, with 40.0% of women utilising digital channels compared to 54.9% of men.
READ MORE: Navy Deploys Sonar Equipment To Recover Crashed NAF Aircraft in Ondo
By comparison, southern geopolitical zones exhibit narrower digital gender divides, ranging from 6.4 percentage points in the South West (84.6% female vs. 91.0% male) to 7.7 percentage points in the South South (79.0% female vs. 86.7% male).
The new report also indicated that a growing proportion of formal credit in Nigeria is being deployed for short-term consumption and daily household survival rather than productive business investment.
The national survey indicated that formal credit adoption nearly doubled from 5.3% of adults in 2023 to 10% (11.9 million people) in 2026; the underlying purpose of these loans shifted markedly toward emergency coping mechanisms.
Loans taken specifically for coping and daily consumption rose by 9.1 percentage points—from 31.7% in 2023 to 40.8% in 2026. Over the same period, formal borrowing allocated to productive business enterprise dropped from 40.2% to 34.3%, while credit for household assets declined from 25.2% to 23.4%.
The surge in credit adoption was most pronounced among informally employed workers, whose formal borrowing rates tripled from 5% in 2023 to 15% in 2026. However, the report highlights significant repayment strain accompanying this expansion, noting that 45.8% of formal credit users experience moderate to severe repayment stress, and 83.8% report ongoing financial distress.
Formal financial inclusion in Nigeria also expanded to 73% of the adult population, equivalent to 87.2 million individuals. However, data from the national study indicates that formal account ownership has not significantly reduced daily economic stress or enhanced household financial resilience.
The survey reveals that 70.1% of formally included adults experience ongoing financial or welfare distress, compared with 71.9% among those without formal accounts. Furthermore, only 31% of formally included Nigerian adults are categorised as financially healthy, while approximately 60.4 million banked citizens remain financially vulnerable or coping. The survey authors characterise the gap between high inclusion numbers and low financial resilience as “participation without progress”.
A2F 2026 KEY INDICATORS AT A GLANCE
├───────────────────────────────┬─────────────────────────
│ Metric Survey Result
├───────────────────────────────┼─────────────────────────
│ Total Adult Population │ 119 million
│ Formal Financial Inclusion │ 73% (87.2 million adults)
│ Digital Financial Services │ 64.4% (77.0 million adults)
│ Ongoing Welfare Distress │ 70.1% (Banked) vs 71.9 (Unbanked)
│ Emergency Liquidity Threshold │ 10.6% can raise ₦156k in 7 days
└───────────────────────────────┴─────────────────────────
The report highlights a substantial gap between account access and emergency capacity. Across the formally included population, only 10.6% of adults reported being able to raise ₦156,000 within seven days without significant difficulty, compared to 3.7% among the unbanked.
“Formal inclusion improves access to emergency liquidity, but the advantage is small in absolute terms,” the report states. In addition, among banked adults with known income buffer durations, 56.8% report being unable to cover living expenses for more than one month if their primary income stops.
The study reports that alternative and informal financial channels—used by 28 million adults for savings and 24 million for borrowing—remain widely utilised due to “speed, simplicity, proximity and flexibility”.
READ MORE: World Bank Raises Nigeria’s 2026 Growth Forecast To 4.3%, Warns Of Election-Year Spending
Physical cash continues to play a primary role in daily transactions for three main structural reasons: 1. Cash Earnings (33%): One-third of adults receive their primary income in cash. 2. Micro-Transaction Convenience (31%): Respondents report cash is faster and more convenient for daily micro-transactions. 3. Emergency Risk Management (19%): 19% of adults maintain cash specifically as a hedge against bank network disruptions.
Addressing cash reliance, the report notes: “In theory, formal digital/banking products should be safer and better suited for financial shocks, but users view cash as the only guaranteed liquidity when crisis strikes. Formal financial channels have a reliability perception deficit. Network downtime, transaction failures, or withdrawal delays cause people to treat cash as an essential risk-management tool rather than just a payment preference.”
System reliability also impacts customer retention. Among single-product customers who encountered service disruptions—such as failed transactions (reported by 38% of broad service users) or delayed refunds (reported by 22%)—10% completely abandoned their service provider.
EFInA and survey stakeholders recommend updating national financial strategy indicators to measure financial health, emergency liquidity, and service reliability alongside traditional account opening targets.